US CPA Accountants and Cross-Border Tax Records
By weiyi weiyi · 2026-11-02
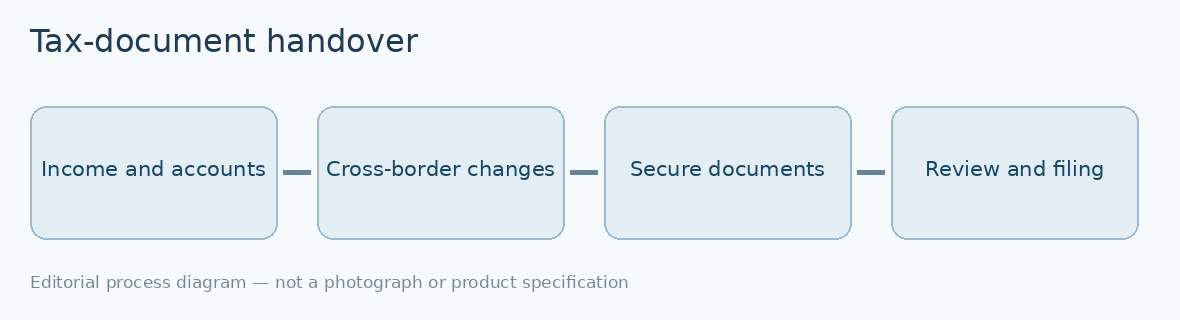
Separate personal and business records at the source. A business owner should be able to identify revenue, bank transactions, card activity, payroll, contractor payments and business expenses without asking the accountant to decode a year's worth of mixed purchases. Reconcile bank and payment-platform balances to the books where feasible. Keep invoices and receipts tied to transaction dates and categories rather than leaving them in a folder named “miscellaneous”. A clean set of records may still contain judgement questions, but it should not contain avoidable arithmetic mysteries.
Prepare a concise list of changes since the prior filing. New employment, a property sale, equity compensation, foreign accounts, business ownership changes or relocation can alter the information needed.
A US CPA accountant can clarify the filing scope after receiving the actual records and facts.
Cross-border situations may create extra reporting obligations, and the applicable rules depend on residency, citizenship, entity structure and other facts. Do not assume that a tax return in one country removes every obligation in another. The accountant needs the relevant timeline and source documents before giving tailored advice. For cross-border clients working with a 美国CPA会计师, a dated list of moves, ownership changes and foreign accounts is more useful than a vague summary.
A checklist for document requests should be specific. “Send bank records” may mean twelve statements, not one screenshot of a current balance. “Send payroll information” may include tax filings and year-end reconciliations as well as a summary spreadsheet. Different businesses require different lists. The value of an experienced professional is partly in spotting what is missing, which becomes much easier when the client can explain their operations and provide a coherent record trail.
A tax return review should allow time for questions rather than treating signature day as a formality. Clients can compare the main figures with their own records, ask about significant changes from the prior year and understand when payments are due. The accountant should explain the scope of the review under the engagement. If a foreign account or business interest has not been mentioned, it is better to raise it before filing than to assume an ordinary questionnaire must have covered every possibility.
Scope should be explicit. Some engagements cover only annual returns; others include bookkeeping, payroll, estimated payments, state filings or correspondence with tax authorities. Ask which tasks are included, which records the client must provide and who is responsible for addressing notices after filing. A low quoted fee can be difficult to compare if the deliverables differ substantially. Written engagement terms protect both sides from misunderstandings about responsibility.
Secure document handling is part of the process. Tax files contain sensitive identification and financial information. Use a suitable portal or another approved secure channel rather than distributing identity documents casually through unprotected messages. Ask who can access the information, how long it is retained and how missing documents are requested. If the client and accountant work across time zones, agree on a practical review calendar rather than relying on last-minute replies.
For a cross-border tax conversation, start by separating the person's tax residency from where their salary is paid or where a company is registered. An overseas bank account does not always create the same reporting duty as foreign earned income. A US-qualified CPA should obtain the facts before offering a filing position: citizenship or residency status, source of income, ownership interests and relevant prior filings. Keep personal documents in a secure channel. A public blog can explain common questions, but it cannot replace advice tailored to an individual's situation and the rules in force for that tax year.
Small businesses can improve handover by reconciling accounts monthly instead of waiting for the year-end. When a payment processor deposits less than the gross sale because it deducted fees, the records should distinguish revenue from processing expense. Otherwise gross receipts may be understated or duplicate amounts can appear during reconciliation. An accountant may need clarification on inventory, owner contributions or personal expenses charged to a business account, so record those decisions while the details are fresh.